Thursday, 24 September 2026
FinsamudraFinsamudra

Banking & NBFCs · Daily brief

Global Fintech Fest 2026: IDFC FIRST Bank CEO V. Vaidyanathan Sees Profitability Improving on $3.6B FCNR(B) Deposits

IDFC FIRST Bank mobilized ₹30,000 crore in foreign currency non-resident deposits under the RBI concessional window, creating a 55 bps funding arbitrage to retire expensive wholesale debt.

30,000CR FCNR(B)

FINSAMUDRA DESK · 10 Sept 2026, 1:14 pm IST · 3 MIN

HERO IMAGE
Image: - FINSAMUDRA

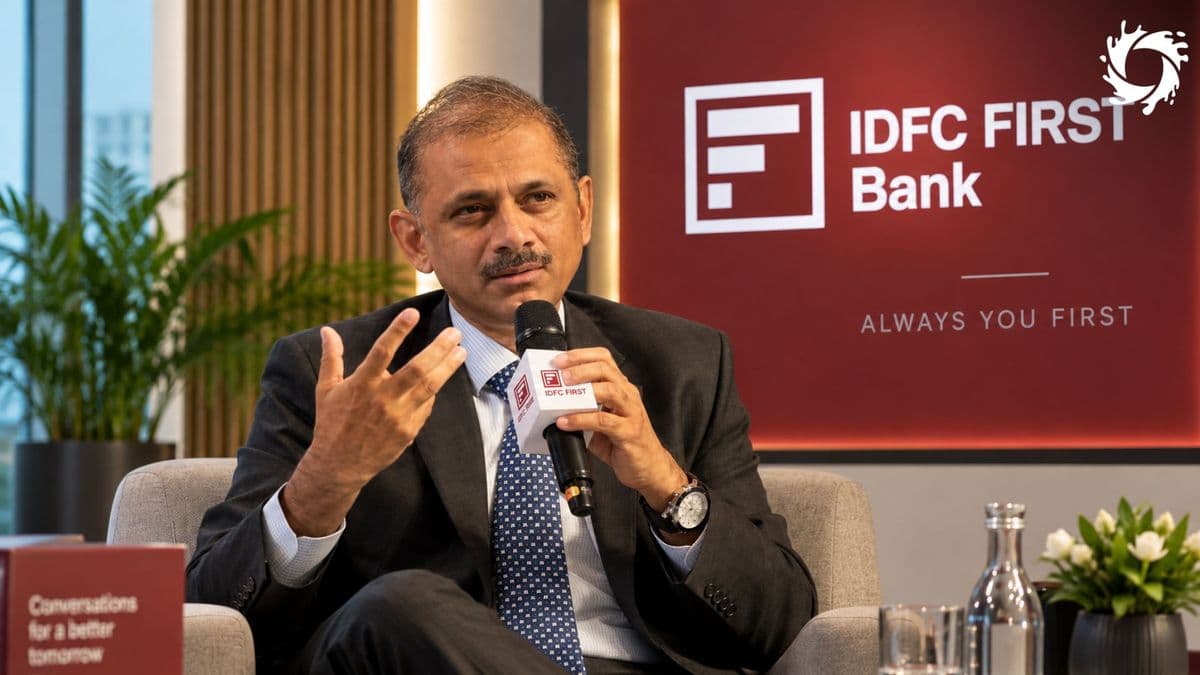
IDFC FIRST Bank has successfully mobilized $3.6 billion (approximately ₹30,000 crore) in Foreign Currency Non-Resident (Bank) deposits under the Reserve Bank of India’s (RBI) concessional swap window, MD and CEO V. Vaidyanathan stated in an exclusive conversation with CNBC-TV18 at the Global Fintech Fest (GFF) 2026 in Mumbai.

The massive foreign currency inflow now accounts for nearly 11 percent of IDFC FIRST Bank’s total deposit base, marking one of the most successful balance sheet optimizations among private sector lenders capitalizing on the central bank's currency swap mechanism. Across the banking system, Indian lenders have mobilized roughly $127 billion under this window.

The 55 bps Cost-of-Funds Arbitrage

Addressing questions on how this substantial influx impacts the bank’s funding profile, Vaidyanathan explained that the foreign currency deposits offer a significant cost advantage over traditional domestic retail and bulk term deposits.

"We raised money at about 5.60% to 5.65% in dollars. When you account for the Cash Reserve Ratio (CRR) and Statutory Liquidity Ratio (SLR) requirements, the fully loaded cost to the bank comes to approximately 6.75%," Vaidyanathan said.

In contrast, prevailing domestic term deposits in India are commanding interest rates between 7.20% and 7.30% or higher. The FCNR(B) deposits therefore provide IDFC FIRST Bank with an immediate ~55 basis point margin arbitrage, substantially reducing its blended cost of incremental liabilities.

Retiring High-Cost Wholesale Liabilities

Crucially, the bank does not intend to let this influx sit idle or trigger aggressive price competition on the lending front. Instead, IDFC FIRST Bank will systematically use the ₹30,000 crore inflow as a substitution tool to pay off high-cost domestic wholesale and certificate of deposit (CD) borrowings as they mature.
"As high-cost domestic bulk deposits mature over the next few quarters, we will simply not renew them. We are substituting expensive domestic deposits with this lower-cost foreign currency pool, which directly benefits our net interest income and net earnings," Vaidyanathan explained.

NIM Optical Compression vs Bottom-Line Expansion

When asked about the short-term impact on Net Interest Margins (NIM), Vaidyanathan conceded that holding large cash balances temporarily depresses reported NIMs on paper, but underscored that underlying profitability will see a noticeable lift.

"When you bring in ₹30,000 crore onto your balance sheet in a short period, it temporarily sits in liquidity instruments or high-grade liquid assets, which creates an optical compression on NIM. But investors must look at absolute profit after tax. As these funds are deployed and expensive debt rolls off by Q3 and Q4, our overall profitability will demonstrably improve."

Maintaining 20% Loan Growth and Underwriting Sanity

Despite sitting on substantial surplus liquidity, Vaidyanathan dismissed speculation that IDFC FIRST Bank would relax underwriting filters or push beyond its established 20 percent annual loan growth trajectory.

"Just because you have a lot of cash doesn't mean you just start putting it out into the market," Vaidyanathan asserted. "We will not dilute credit quality or chase sub-optimal risk. Our retail and MSME loan books are compounding at a healthy 20%, and we intend to maintain that exact discipline."

More on IDFC FIRST

Every story on IDFC FIRST

Sources


Free daily briefing

The day's money story, before the market opens

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn — with the Finsamudra take on what it means for lending.