Thursday, 24 September 2026
FinsamudraFinsamudra

Banking & NBFCs · Daily brief

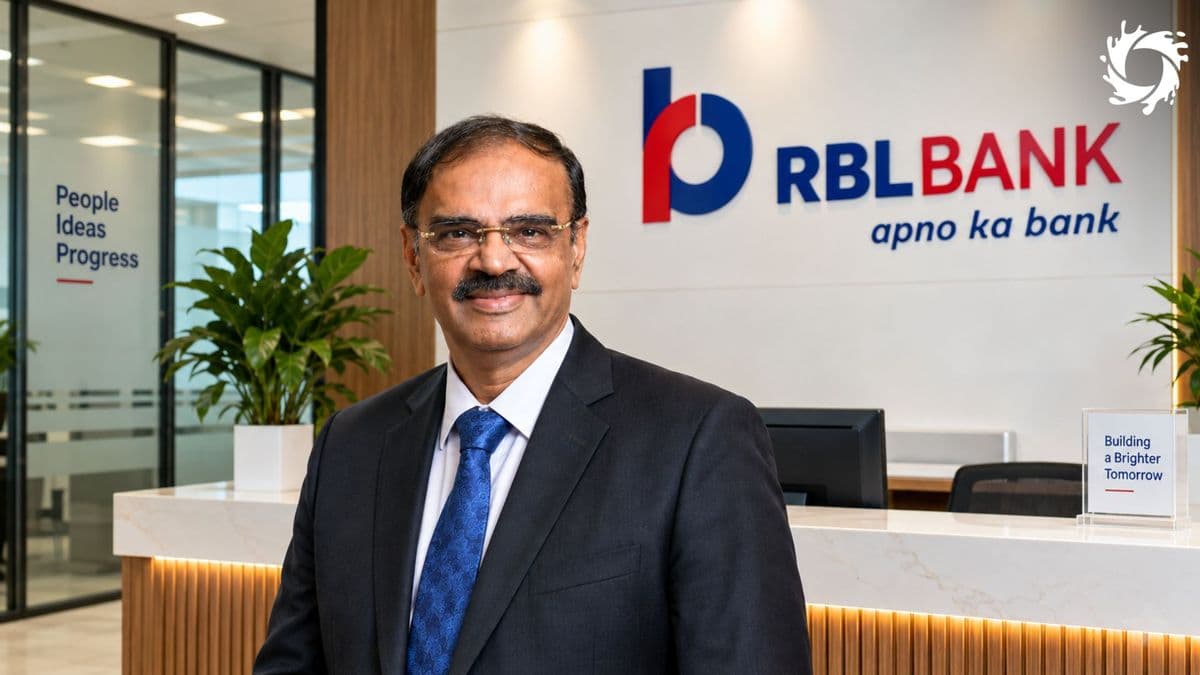
The Turnaround Was Real. But Why RBL Bank Still Needed a $2.75 Billion Foreign Bailout

R Subramaniakumar resolved DHFL, cut RBL Bank's bad loans from 4.40% to 1.45%, and proved the market wrong after a brutal 22% panic. But in Indian banking, an asset cleanup is only half the battle.

FINSAMUDRA DESK · 23 Sept 2026, 2:49 pm IST · 3 MIN

2.75 BILLION DOLLARS RBL BANK
HERO IMAGE
Image: - FINSAMUDRA

The Surgeon's Scorecard: What Subramaniakumar Actually Built

Subramaniakumar’s tenure was a masterclass in balance-sheet de-risking. He inherited a bank that had posted a net loss of ₹74.74 crore in FY22, plagued by corporate loan write-offs and underwriting skittishness.

RBL BANK FINANCIAL METRICS (FY22 – FY26)

----------------------------------------------------------------------

Metric FY22 FY24 (Peak) FY25 (Stress) FY26

----------------------------------------------------------------------

Gross NPA (%) 4.40% 2.65% 1.80% 1.45%

Net Profit (Cr) -₹74.7 Cr ₹1,168 Cr ₹695 Cr ₹822 Cr

Net Worth (Cr) ~₹12,600 Cr ~₹14,500 Cr ~₹15,200 Cr ~₹16,400 Cr

CRAR (%) 16.2% 16.1% 15.8% 15.3%

----------------------------------------------------------------------

Post-Emirates NBD Infusion (June 2026): CRAR surges to >25%; Net Worth reaches >₹42,000 Cr.

By March 2026:

  • Asset Quality Restored: Gross NPAs plummeted from 4.40% to 1.45%, outperforming several older private sector peers.
  • Return to Sustained Profitability: The bank turned around to post ₹1,168 crore in FY24 profit before navigating the FY25 unsecured lending headwinds with an ₹822 crore profit in FY26.
  • Corporate Governance Reinforced: Risk architecture was recalibrated, institutional underwriting tightened, and the regulator's oversight concerns systematically dismantled.

Yet, despite this operational victory, RBL Bank’s board agreed to cede 60% control to Dubai’s largest banking conglomerate.
The Structural Trap: Why the NPA Fix Was Never Enough

The decision to sell control to Emirates NBD was not an admission of failure; it was a cold acknowledgment of the structural reality governing Indian banking.

1. The Cost-of-Funds Disadvantage

A bank does not compete purely on how cleanly it recovers loans; it competes on how cheaply it buys money. India’s dominant private banking trio—HDFC Bank, ICICI Bank, and Kotak Mahindra Bank—possess massive branch footprints that yield sticky, low-cost Current and Savings Account (CASA) ratios of 40% to 45%.

As a mid-sized lender, RBL Bank had to constantly pay 100 to 150 basis points more on retail term deposits to prevent deposit flight. When interest rates remained higher for longer, RBL’s net interest margins (NIMs) suffered disproportionate compression.

2. The Unsecured Lending Paradox

To compensate for its higher cost of deposits, RBL Bank had no choice but to deploy capital into high-yield, high-risk assets: co-branded credit cards (most notably with Bajaj Finance) and microfinance (JLG loans).

While this generated windfall margins in benign credit environments (fueling the record FY24 earnings of ₹1,168 crore), it left the bank exposed when regulatory risk weights were hiked on unsecured consumer credit in FY25. Profits crashed by 40% to ₹695 crore almost overnight. Cleaning bad loans did not eliminate cyclical vulnerability.

3. The Scale Moat

With an asset book of just over ₹1.2 lakh crore, RBL Bank lacked the scale required to fund heavy multi-year enterprise AI investments, underwrite billion-dollar corporate syndications, or build nationwide physical distribution without crushing its cost-to-income ratio.


The Emirates NBD Synthesis: A Sovereign Balance Sheet

The $2.75 billion primary capital infusion from Emirates NBD fundamentally rewrites RBL Bank's destiny:

  1. Balance-Sheet Fortress: The capital injection nearly triples RBL Bank’s net worth to over ₹42,000 crore, propelling its Capital to Risk-Weighted Assets Ratio (CRAR) past 25%.
  2. Wholesale Credit Rating Uplift: With majority backing from a sovereign-linked UAE banking titan, RBL Bank’s credit ratings will re-rate upward, shaving significant basis points off its wholesale borrowing and bond issuances.
  3. The UAE-India CEPA Highway: Bilateral trade between India and the UAE is accelerating past $100 billion under the Comprehensive Economic Partnership Agreement. RBL Bank is now the exclusive domestic pipeline for Emirates NBD’s vast trade finance, multinational treasury, and non-resident Indian (NRI) remittance flows.

Sources


Free daily briefing

The day's money story, before the market opens

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn — with the Finsamudra take on what it means for lending.